
Resin & Steel
Weekly Market Brief
Stronger resin futures, firmer U.S. steel offers and a less uniform global picture. Six source-linked cards for a quick read; the full review explains the price bases and U.S. implications.
Download the six-card brief (PNG)
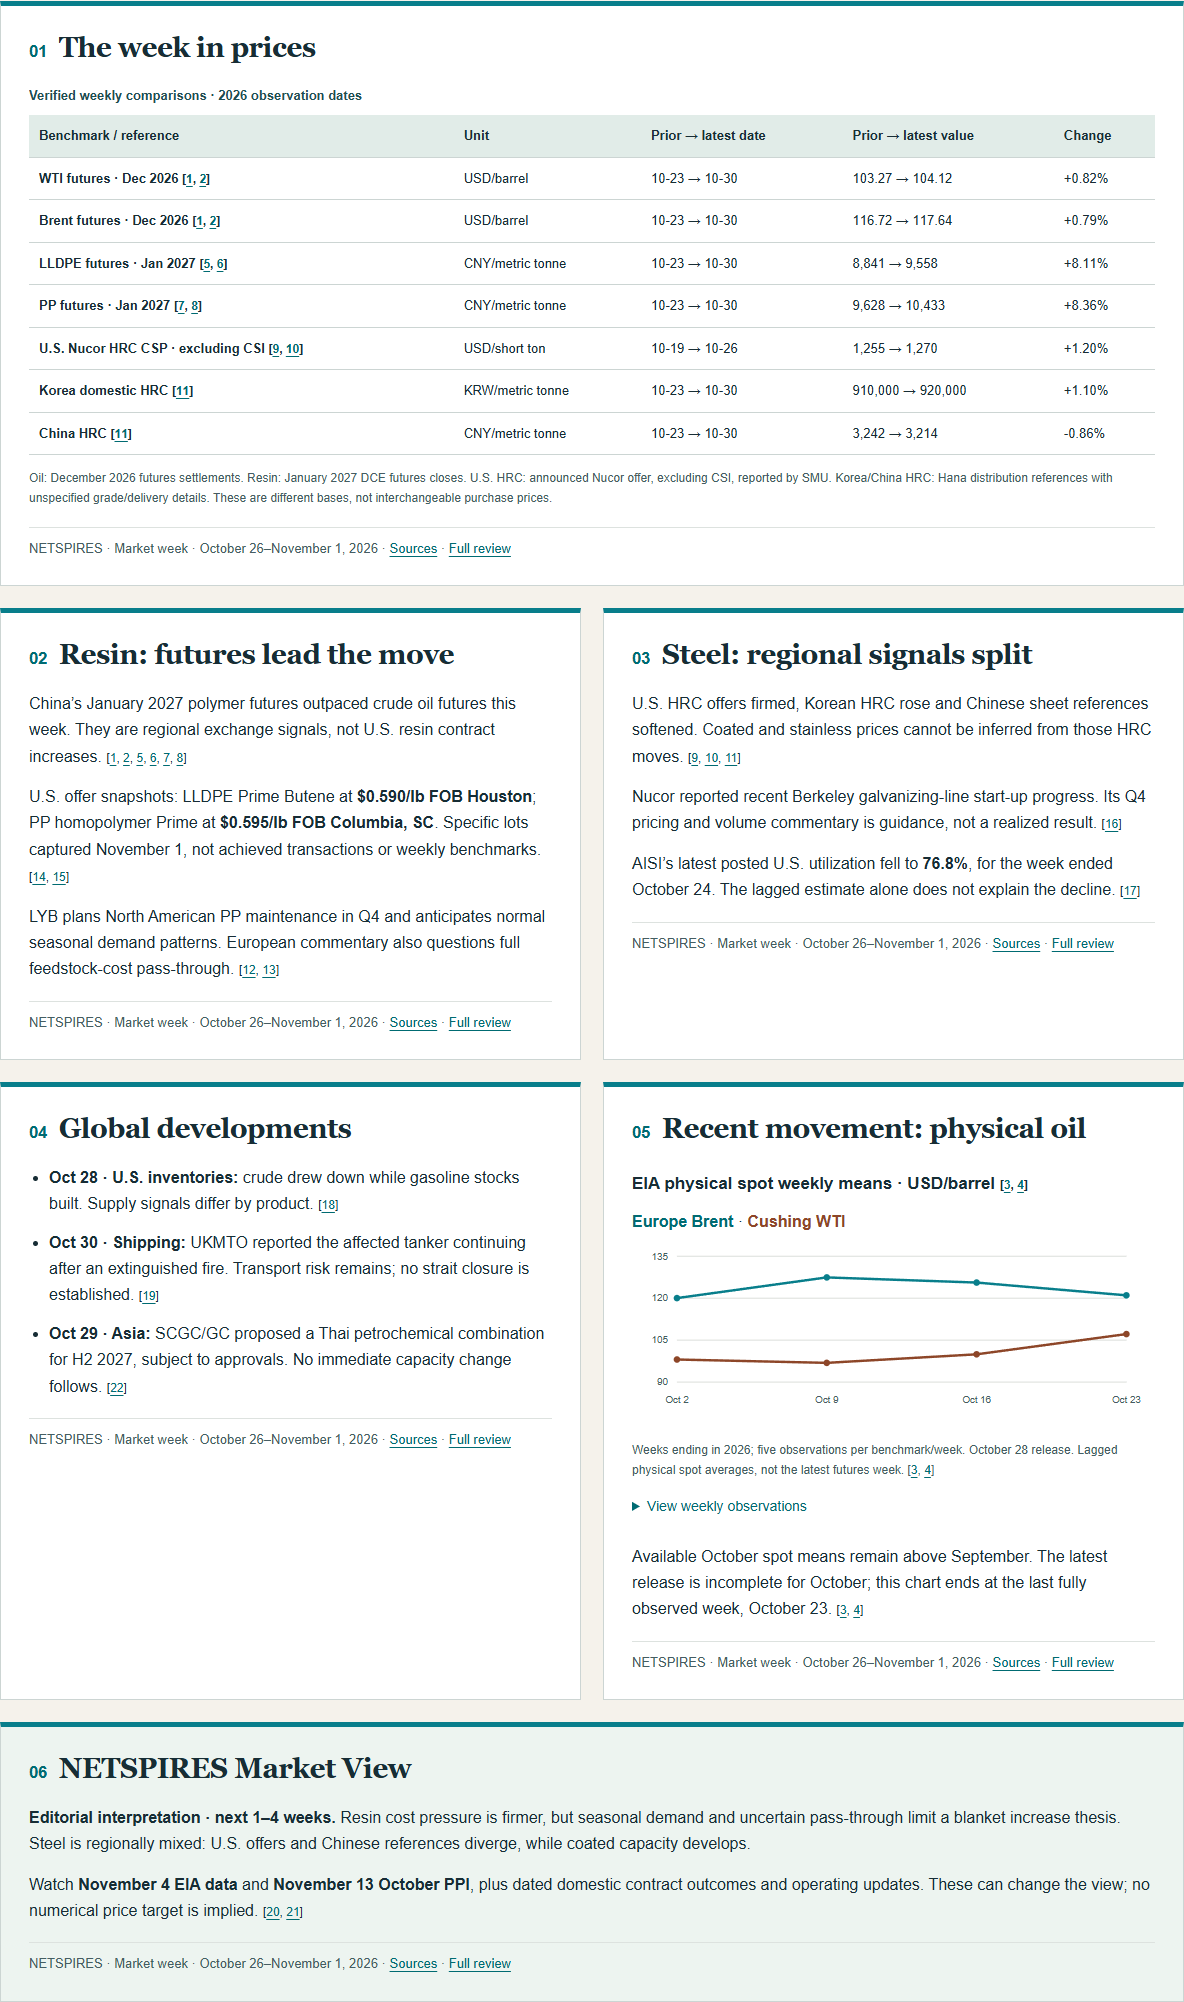
01The week in prices
| Benchmark / reference | Unit | Prior → latest date | Prior → latest value | Change |
|---|---|---|---|---|
| WTI futures · Dec 2026 [1, 2] | USD/barrel | 10-23 → 10-30 | 103.27 → 104.12 | +0.82% |
| Brent futures · Dec 2026 [1, 2] | USD/barrel | 10-23 → 10-30 | 116.72 → 117.64 | +0.79% |
| LLDPE futures · Jan 2027 [5, 6] | CNY/metric tonne | 10-23 → 10-30 | 8,841 → 9,558 | +8.11% |
| PP futures · Jan 2027 [7, 8] | CNY/metric tonne | 10-23 → 10-30 | 9,628 → 10,433 | +8.36% |
| U.S. Nucor HRC CSP · excluding CSI [9, 10] | USD/short ton | 10-19 → 10-26 | 1,255 → 1,270 | +1.20% |
| Korea domestic HRC [11] | KRW/metric tonne | 10-23 → 10-30 | 910,000 → 920,000 | +1.10% |
| China HRC [11] | CNY/metric tonne | 10-23 → 10-30 | 3,242 → 3,214 | -0.86% |
Oil: December 2026 futures settlements. Resin: January 2027 DCE futures closes. U.S. HRC: announced Nucor offer, excluding CSI, reported by SMU. Korea/China HRC: Hana distribution references with unspecified grade/delivery details. These are different bases, not interchangeable purchase prices.
02Resin: futures lead the move
China’s January 2027 polymer futures outpaced crude oil futures this week. They are regional exchange signals, not U.S. resin contract increases. [1, 2, 5, 6, 7, 8]
U.S. offer snapshots: LLDPE Prime Butene at $0.590/lb FOB Houston; PP homopolymer Prime at $0.595/lb FOB Columbia, SC. Specific lots captured November 1, not achieved transactions or weekly benchmarks. [14, 15]
LYB plans North American PP maintenance in Q4 and anticipates normal seasonal demand patterns. European commentary also questions full feedstock-cost pass-through. [12, 13]
03Steel: regional signals split
U.S. HRC offers firmed, Korean HRC rose and Chinese sheet references softened. Coated and stainless prices cannot be inferred from those HRC moves. [9, 10, 11]
Nucor reported recent Berkeley galvanizing-line start-up progress. Its Q4 pricing and volume commentary is guidance, not a realized result. [16]
AISI’s latest posted U.S. utilization fell to 76.8%, for the week ended October 24. The lagged estimate alone does not explain the decline. [17]
04Global developments
- Oct 28 · U.S. inventories: crude drew down while gasoline stocks built. Supply signals differ by product. [18]
- Oct 30 · Shipping: UKMTO reported the affected tanker continuing after an extinguished fire. Transport risk remains; no strait closure is established. [19]
- Oct 29 · Asia: SCGC/GC proposed a Thai petrochemical combination for H2 2027, subject to approvals. No immediate capacity change follows. [22]
05Recent movement: physical oil
Europe Brent · Cushing WTI
Weeks ending in 2026; five observations per benchmark/week. October 28 release. Lagged physical spot averages, not the latest futures week. [3, 4]
View weekly observations
| Week ending | Europe Brent FOB | Cushing WTI FOB | Observations B / W |
|---|---|---|---|
| 2026-10-02 | 120.03 | 98.07 | 5 / 5 |
| 2026-10-09 | 127.43 | 96.88 | 5 / 5 |
| 2026-10-16 | 125.59 | 99.93 | 5 / 5 |
| 2026-10-23 | 121.02 | 107.17 | 5 / 5 |
October 28 EIA release. The next week has only October 26–27 observations and is excluded. These lagged spot means are separate from October 23–30 futures returns.
Available October spot means remain above September. The latest release is incomplete for October; this chart ends at the last fully observed week, October 23. [3, 4]
06NETSPIRES Market View
Editorial interpretation · next 1–4 weeks. Resin cost pressure is firmer, but seasonal demand and uncertain pass-through limit a blanket increase thesis. Steel is regionally mixed: U.S. offers and Chinese references diverge, while coated capacity develops.
Watch November 4 EIA data and November 13 October PPI, plus dated domestic contract outcomes and operating updates. These can change the view; no numerical price target is implied. [20, 21]
Sources and data notes
- Xinhua — December crude oil futures settlements — Published October 24; October 23 observations
- Xinhua — December crude oil futures settlements — Published October 31; October 30 observations
- EIA — Europe Brent physical spot history — October 28 release; observations through October 27
- EIA — Cushing WTI physical spot history — October 28 release; observations through October 27
- CCFGroup — January 2027 LLDPE close — October 23, 2026
- CCFGroup — January 2027 LLDPE close — October 30, 2026
- CCFGroup — January 2027 PP close — October 23, 2026
- CCFGroup — January 2027 PP close — October 30, 2026
- Steel Market Update — Nucor announced HRC CSP — October 19, 2026
- Steel Market Update — Nucor announced HRC CSP — October 26, 2026
- Hana Securities — Steel & Metals Weekly, page 6 — Published November 1, 19:38 Korea; November 2 cover; October 30 / prior-week table
- myCEPPI via PlasticPortal — Year-end polymer price scenarios — October 30, 2026
- LyondellBasell — Third-quarter results, SEC-hosted original — October 30, 2026; Q4 outlook is guidance
- The Plastics Exchange — LLDPE film offer, lot 86803 — Captured November 1, 14:43:59 CST; listing publication time unspecified
- The Plastics Exchange — PP homopolymer offer, lot 86864 — Captured November 1, 14:44:00 CST; listing publication time unspecified
- Nucor — Third-quarter results and operating update — October 26, 2026
- AISI — Weekly raw steel production estimate — Inspected November 1; latest posted week ended October 24
- EIA — Archived weekly petroleum summary — October 28 release; week ended October 23
- UKMTO — Warning 187-26, Update 001 — Incident October 29; update October 30, 01:50 UTC
- BLS — Producer Price Index release schedule — Inspected November 1, 2026
- EIA — Weekly petroleum release schedule — Inspected November 1, 2026
- SCGC — Proposed Thai petrochemical combination with GC — October 29, 2026; completion target H2 2027, conditional
Weekly changes are (latest / prior − 1) × 100 on matching contracts or stated reference series. Monthly and weekly spot means are derived from inspected EIA daily observations. Futures, reported distribution references, producer offers, individual listings, operating estimates and editorial interpretation are separate categories. Source documents were directly inspected; detailed evidence and arithmetic accompany this review. The supplied Korean infographic was used only as a structural reference. This early Sunday snapshot does not claim coverage through the later 18:00 cutoff.